Peirce’s last day at SEC leaves crypto rulemaking with Atkins and Uyeda
The Crypto Task Force leader departs October 2 with custody, transfer-agent and permanent tokenized-market rules still on the agenda.
Page 3
The Crypto Task Force leader departs October 2 with custody, transfer-agent and permanent tokenized-market rules still on the agenda.
Quarterly eligibility checks and custody controls would govern advisers holding client assets; the proposal still faces public comment.
The mainnet upgrade adds state-dependent transaction eligibility and B20 issuer functions, while dynamic node upgrades remain in metrics-only mode.
The September 15 default judgment imposes shared restitution and penalties; Wednesday’s announcement also details separate consent orders.
The group backs Husted, Hinson and Pappas while expanding its House campaign.
UK crypto businesses have until February 28 to apply; existing money laundering registrations will not automatically convert.
Three new letters seek identity checks, employee trading safeguards and suspicious-trade referrals by October 13.
Four new FAQ answers spell out when derivatives firms may use tokenized permitted investments and blockchain records, while keeping existing custody and production duties in place.
In a September 23 speech, the SEC commissioner called for reusable proofs of specific facts. Existing customer-identification rules still apply.
The temporary Innovation Exemption permits controlled tokenized-stock venues and liquidity pools while the agency studies permanent rules.
The SEC’s September proposal and follow-up comments put tokenized securities infrastructure in front of the agency’s core recordkeeping rules.
Brevo reports 138 accessed accounts; Trezor says 347,149 marketing contacts were exported from its list.
The September 15 procedural vote blocked debate on H.R. 3633; the revised ethics and stablecoin language remains a proposal.
The September 15 cloture motion failed 49–50. This source collection preserves the pre-vote reporting; the later result is confirmed by Senate roll call 234.
Treasury is taking comments until October 19 on who can issue and sell stablecoins in the US. Issuers need a license by January 18, 2027. Service providers may offer and sell licensed coins by July 18, 2028. Jones Day says final rules will not pull that date forward. Issuers already cannot pay interest. Banks are still fighting affiliate and exchange rewards that look like yield. That dispute is in the Clarity bill. Cloture is September 15 at 2:15 p.m. ET, a 60-vote test, not final passage.
Treasury's June 2026 action designated Nobitex and other Iranian exchanges. The 2026 National Money Laundering Risk Assessment identifies provider control failures, jurisdiction shopping, and off-platform activity as recurring digital-asset laundering risks. OFAC explains why Iranian digital-asset exchanges are blocked.
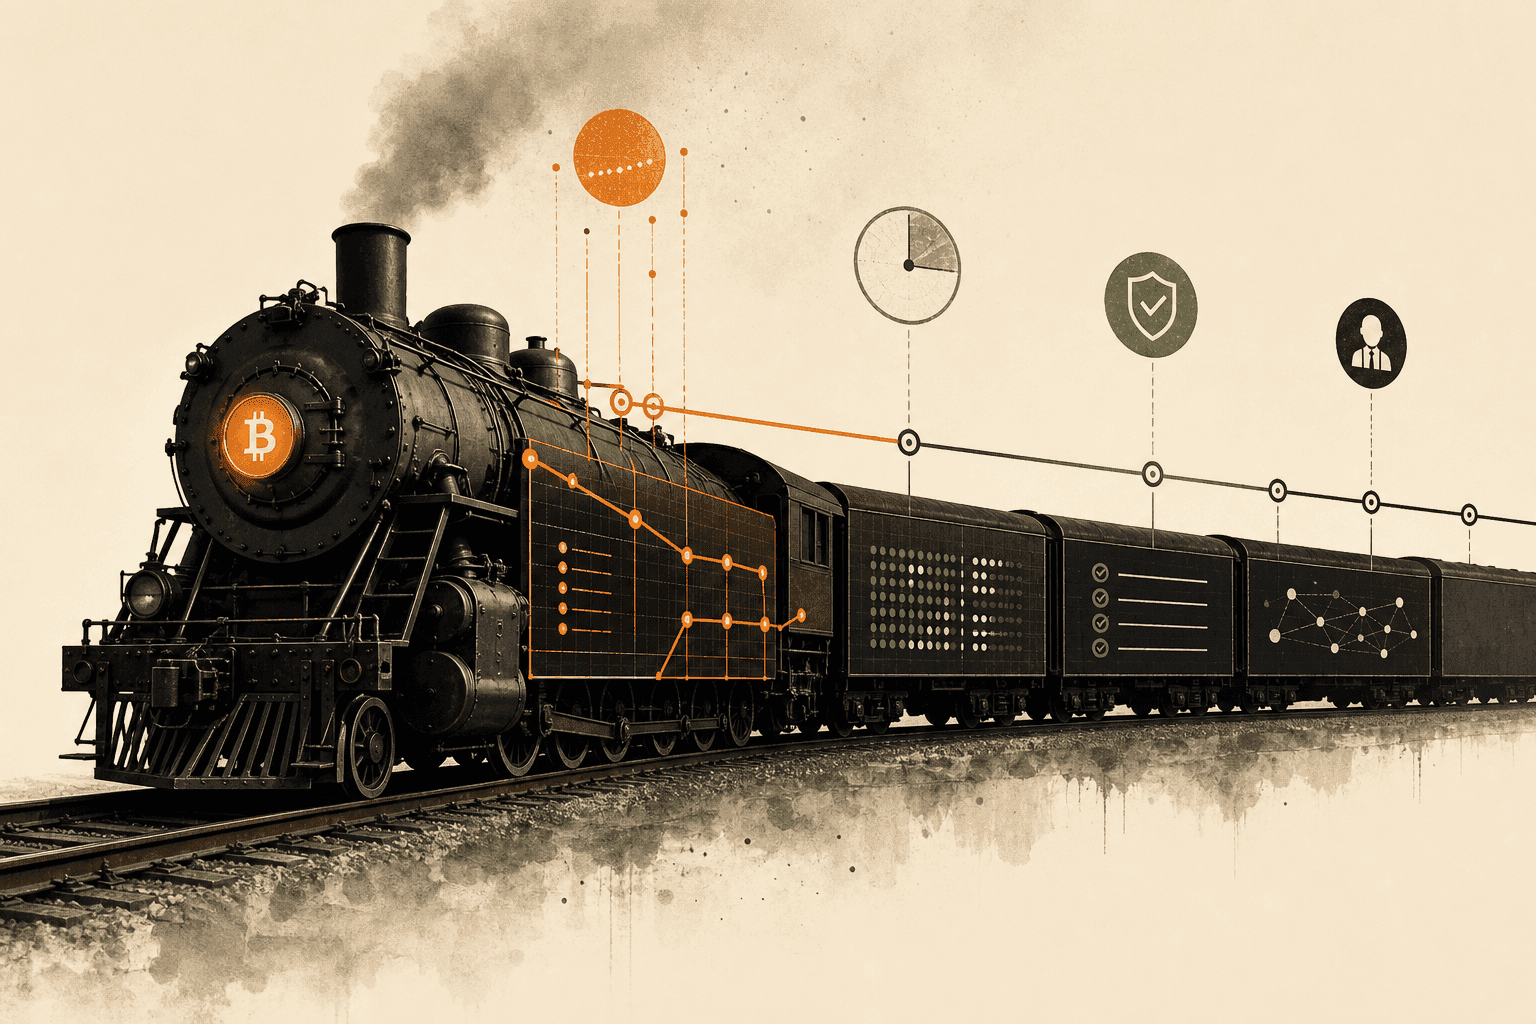
Consensus did not fail. Official advisories cover wallet-migration, private-broadcast, crash, denial-of-service, and disk risks. Wallet code, optional flags, and release adoption are their own security surface.
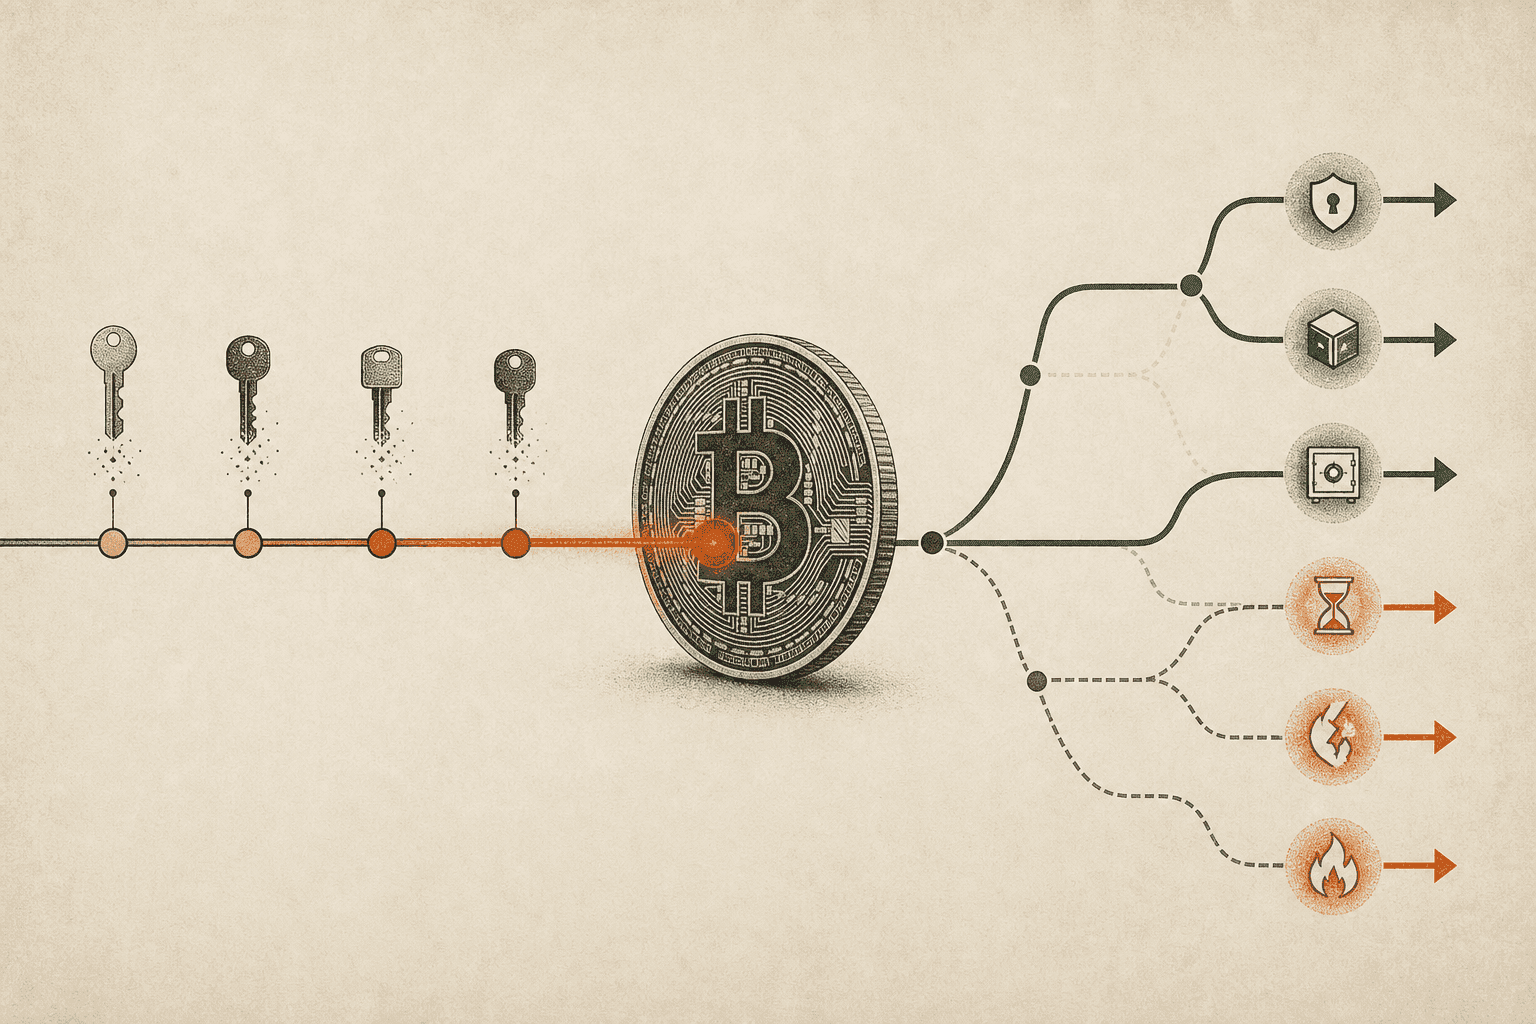
BIP 360 proposes an optional output type intended to reduce exposure to future quantum key recovery. BIP publication is an editorial milestone, not evidence of community consensus, deployment, or adoption.
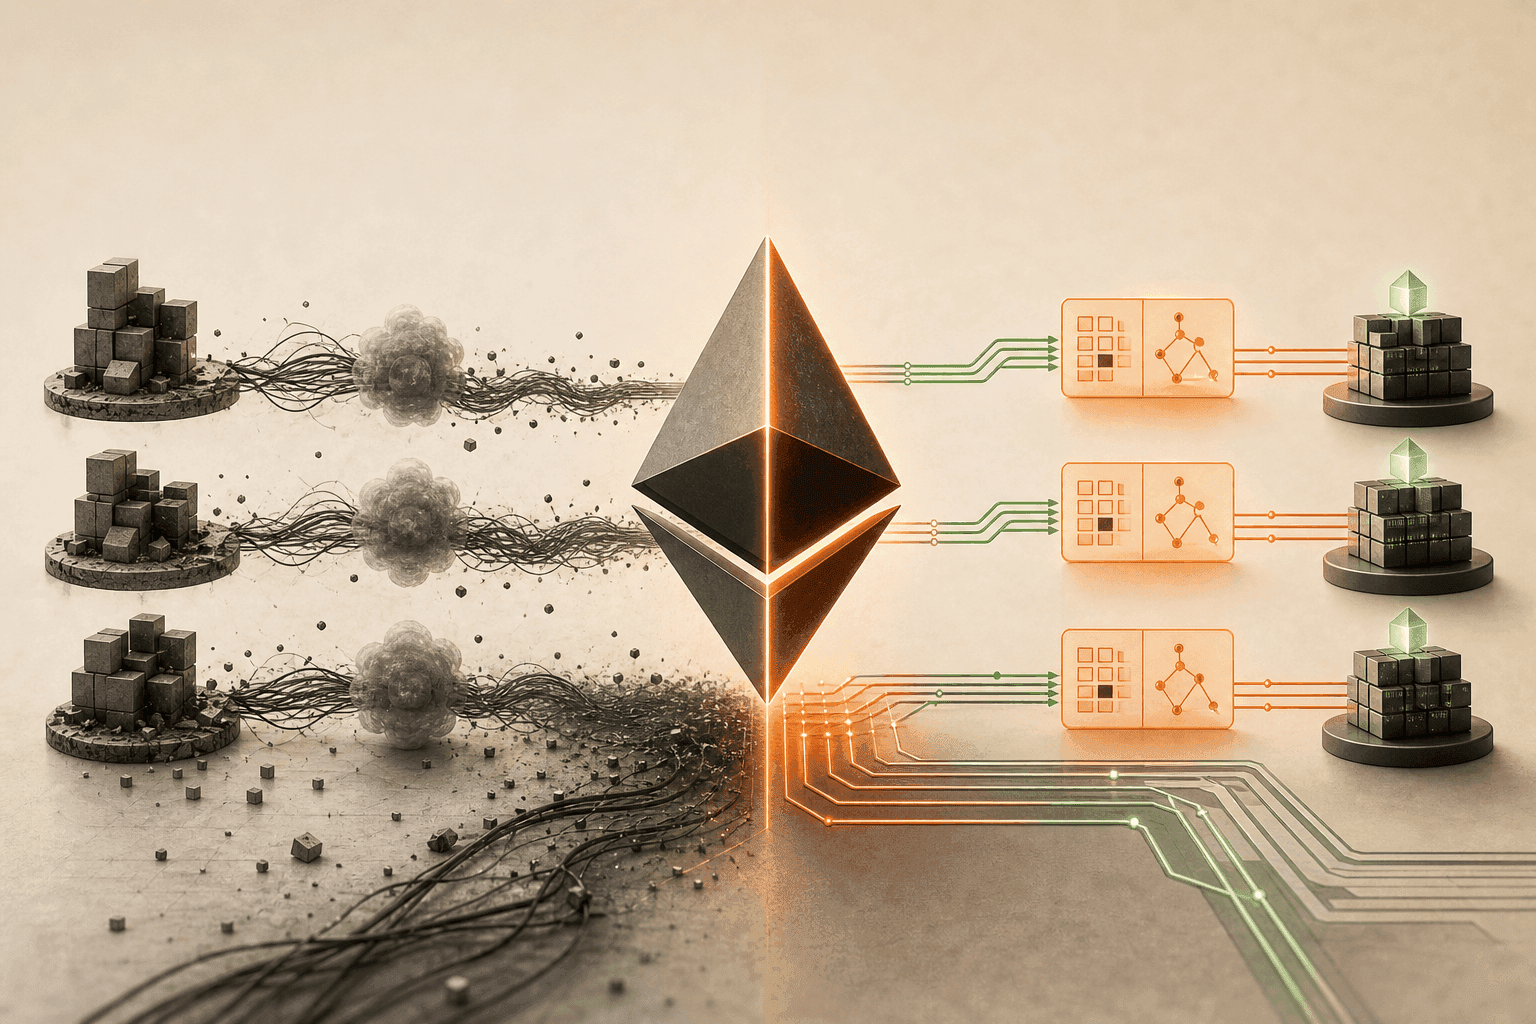
Glamsterdam tries to buy a higher gas limit by moving block building into the protocol. Multi-client devnets are testing ePBS, gas repricing, and block-level access lists. That work is still on a devnet, not mainnet.
A vault is not a legal category. It is a control model. Peirce's statement on crypto vaults and lending strategies warns that onchain yield activity can still fall inside federal securities law when someone performs essential choices.
CFTC staff addresses foreign-futures treatment and a conditional no-action position involving customer crypto collateral and a foreign broker affiliate. A U.S. listing changes the venue. It does not turn a perpetual into spot. The contract still has no expiry and still pays funding.
SEC staff distinguishes issuer-sponsored, custodial, linked, and synthetic tokenization models and explains how holder rights can differ. Rights follow the legal instrument and the ownership file, not the logo the token happens to track.
The IMF separates total stablecoin volume from payment-related flows and compares payment benefits with currency substitution, capital-flow, reserve, and policy risks. A cheaper remittance still imports the issuer, the freeze rule, and the foreign reserve.
Treasury's April 2026 notice outlines proposed AML and sanctions-program duties for permitted payment stablecoin issuers. A permitted-issuer label is not uninterrupted redemption. The operating questions are who screens, who freezes, what the reserves actually are, and how cash-out works when it is tested.